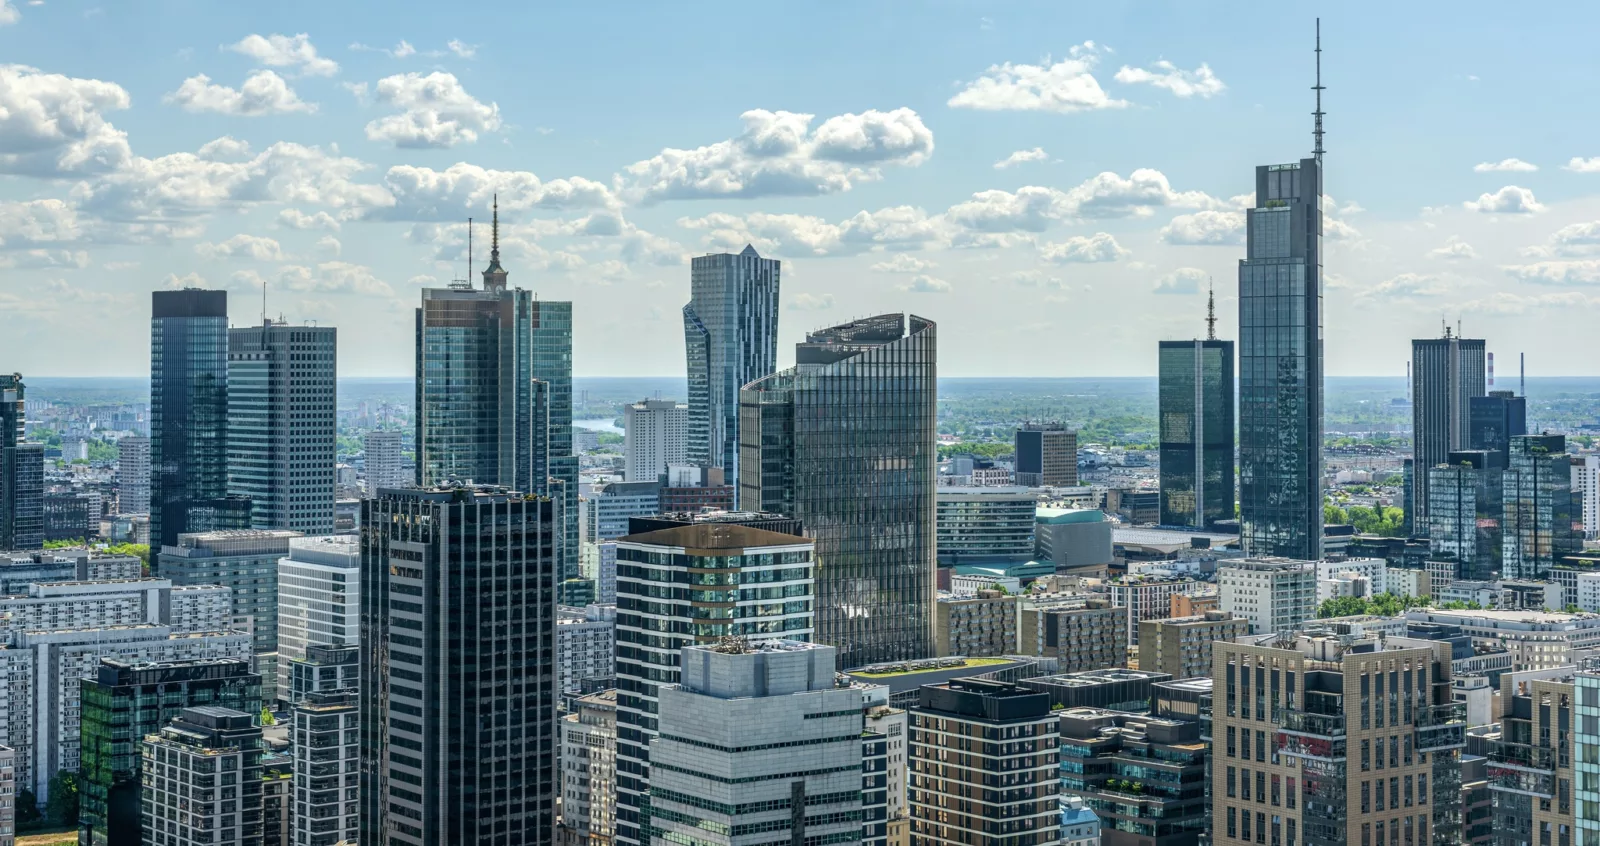


The Warsaw office market accelerated significantly in the first half of 2026. Tenants leased almost 417,000 sq m of office space, 38% more than in the corresponding period of the previous year. The second quarter was particularly active, accounting for as much as 70% of total demand recorded during the first half.
At the same time, limited development activity, the refurbishment of older properties and the conversion of some buildings to alternative uses are gradually reducing the amount of available space. The vacancy rate fell to 8.5%, while rents for the best offices have already exceeded €30 per sq m per month.
These are among the findings of the report Warsaw Office Market: Status, Trends and Forecasts — H1 2026, prepared by Agnieszka Bykowska and Przemysław Urbański of Avison Young.
Warsaw office market in figures
At the end of the first half of 2026:
- modern office stock totalled 6.24 million sq m;
- new supply reached 45,200 sq m;
- 131,200 sq m was under construction or refurbishment;
- demand amounted to 416,600 sq m, up 38% year on year;
- the overall vacancy rate fell to 8.5%;
- the vacancy rate in central locations stood at 4.8%;
- 11.8% of office stock outside the centre remained vacant.
The vacancy rate declined by one percentage point compared with the previous quarter and by 2.3 percentage points year on year.
Warsaw gains 45,000 sq m of new office space
The Warsaw market expanded by 45,210 sq m of office space in the first half of 2026. New supply came from the Studio A and Vena projects, as well as from the refurbishment of buildings at 26–26a Przemysłowa Street.
The new office buildings were completed during the first quarter, while the second phase of the Przemysłowa complex refurbishment was delivered in the second quarter.
However, the overall balance of space available on the market remains under pressure. Ongoing refurbishments, redevelopments and conversions have resulted in the withdrawal of more than 70,000 sq m of office space since the beginning of the year.
This means that more space has temporarily or permanently disappeared from the market than has been delivered through new developments.
Development activity remains limited
At the end of June, a total of 131,200 sq m of office space was under construction or undergoing extensive refurbishment. Almost all new projects are located in central zones.
The developments currently under way are scheduled for completion between 2026 and 2028. However, only 3,900 sq m of new space is expected to be delivered by the end of this year, in a single building at 533 Puławska Street.
Such limited supply means that tenants seeking large, modern offices in attractive locations will have increasingly fewer options. The availability of modules exceeding 5,000 sq m is particularly restricted.
The shortage of large office units may make relocations and expansions more difficult for companies planning to increase employment or consolidate several locations.
Office demand increases by 38%
A total of 416,600 sq m of office space was leased in Warsaw during the first half of 2026, representing an increase of 38% compared with the previous year.
The strong recovery was driven by the second quarter, which accounted for approximately 70% of the total transaction volume recorded during the six-month period.
The city centre, Służewiec and the Central Business District continued to attract the greatest tenant interest. Together, these three zones accounted for 80% of total demand.
The transaction structure was almost evenly divided between renegotiations of existing agreements, which accounted for 48% of demand, and new leases, which represented 46%. The remaining 6% involved expansions of existing office space.
Major companies renegotiate their leases
Five lease transactions exceeding 10,000 sq m were completed during the first half of the year. All of them were finalised in the second quarter.
The two largest agreements, each covering more than 20,000 sq m, involved lease renegotiations in buildings located in central zones.
The growing proportion of renegotiations reflects the limited availability of large office spaces and the small number of new developments. Companies occupying attractive offices are increasingly choosing to remain in their current locations rather than risk difficulties in finding comparable space elsewhere.
This trend may further restrict availability for new and smaller tenants, particularly in buildings where major occupiers have priority rights to renew their leases or expand the space they occupy.
Public-sector activity is increasing
The public sector is playing an increasingly important role in the Warsaw office market. Government institutions were responsible for two of the five largest transactions completed in the first half of 2026.
According to Avison Young, the importance of this segment in the commercial market is expected to continue growing. Public institutions are increasingly seeking modern, well-connected and energy-efficient buildings.
This may intensify competition for the largest office modules, particularly in buildings offering an appropriate level of security, accessibility and technical infrastructure.
Central Warsaw vacancy rate falls to 4.8%
Strong tenant activity resulted in a marked decline in the availability of office space.
At the end of June, the vacancy rate across Warsaw stood at 8.5%. In central zones, it fell to just 4.8%, while outside the centre it reached 11.8%.
The difference between the city centre and other districts shows that demand is concentrated primarily in the best locations and in buildings offering high-quality space, convenient public transport connections and solutions aligned with environmental requirements and employee expectations.
With only a limited number of new projects under development, the vacancy rate may continue to decline, particularly in the most competitive parts of the city.
Companies begin office searches earlier
The shrinking supply is prompting tenants to begin relocation and lease renegotiation processes earlier.
“We expect the vacancy rate to continue falling, particularly in the most competitive locations and highest-quality buildings. Growing difficulties in securing appropriate space are encouraging companies to begin their office searches and renegotiations earlier. This trend will continue to strengthen,” says Przemysław Urbański, Director of Office Agency at Avison Young.
He notes that the rising number of lease renewals may further restrict the amount of space available to companies entering the market.
“The growing proportion of renegotiations will limit availability for new and smaller tenants, especially in buildings where key occupiers have priority rights to lease or expand,” Urbański adds.
Prime office rents exceed €30 per sq m
The imbalance between rising demand and limited supply is expected to put further pressure on rents.
Rents in Warsaw’s best office buildings have already exceeded €30 per sq m per month. According to the report’s authors, there is room for further increases, particularly in new and refurbished properties located in the city centre.
Rental costs are being driven not only by the small number of new developments but also by the limited availability of large office units and increasingly demanding requirements concerning quality, energy efficiency and ESG standards.
Owners of the best properties are likely to gain an increasingly strong negotiating position. Tenants, meanwhile, will need to consider not only base rent but also fit-out costs, service charges and the expense of adapting space to changing working models.
Warsaw enters a period of office supply shortages
The outlook for the coming quarters points to a further decline in the availability of office space. Demolitions, refurbishments and conversions of older office buildings will continue to reduce stock, while new supply is expected to remain limited.
The greatest difficulties may affect companies requiring several thousand square metres in a single building. Restricted availability may encourage them to extend existing agreements, begin searches further in advance or consider less central locations.
For owners of high-quality office buildings, this creates a favourable outlook. Tenants, however, will operate in an environment characterised by fewer options, higher rents and stronger competition for the best available space.
Source: Managerplus.pl / Avison Young