Fragment from the investment report “Retail parks everywhere?” prepared by Avison Young in cooperation with CMS (a leading law firm active in the commercial real estate market, including retail parks), BIG Poland (an active investor that entered the Polish retail park market in 2022 and has already completed its 10th acquisition in Poland), and the Polish Council of Shopping Centres (PRCH), which initially focused on larger shopping centers but in recent years has actively promoted retail parks as well.
Retail Parks Everywhere?
How it started
The retail park sector in Poland dates back to the late 1990s, tied to the country’s political transformation. Early pioneers developed projects on the outskirts of large metropolitan areas, creating the first shopping destinations that were later complemented by additional retail formats.
Over the past three decades, the sector has grown in waves. By 2019, the market offered 1.5 million sq m GLA in retail parks larger than 5,000 sq m. The COVID-19 pandemic in 2020 highlighted the resilience and investment appeal of this format. Thanks to their open design, retail parks were less affected by lockdown restrictions. At the same time, consumer demand shifted toward local, convenient shopping, reinforcing investor confidence in the format. This triggered a construction boom.
Between 2020 and 2024, retail parks over 5,000 sq m GLA added another 1.5 million sq m. In the first half of 2025 alone, 120,000 sq m were delivered, with another 340,000 sq m expected in the second half. Based on investor data, 2026 should bring around 500,000 sq m of new space.
Market Size and Structure
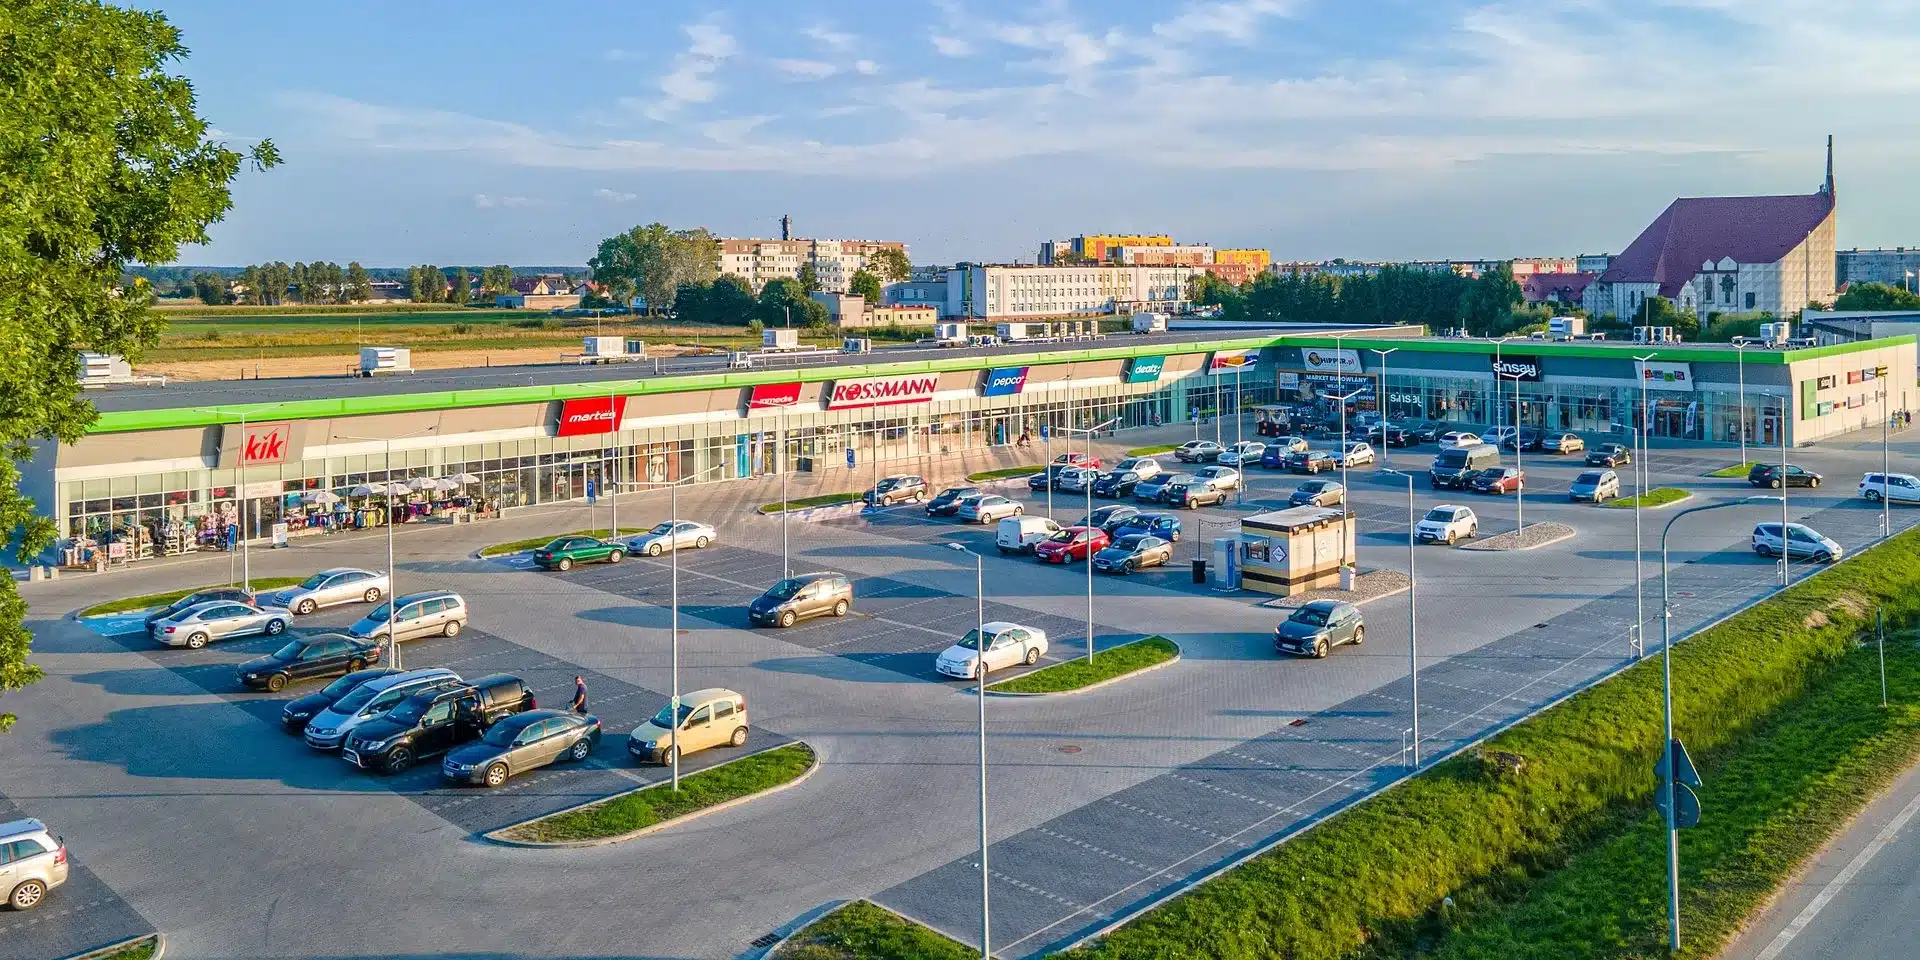
Today, Poland has over 290 large retail parks (above 5,000 sq m GLA) with a total of 3.2 million sq m GLA, representing 21% of modern retail stock—double the share in 2010.
Since 2020, over 70% of new projects have been mid-sized parks (5,000–10,000 sq m GLA). Nearly 60% of new investments are in towns with fewer than 50,000 residents.
Alongside the larger parks, there are also over 400 small convenience parks (2,000–5,000 sq m), adding 1.3 million sq m GLA nationwide.
Development Trends
The Polish retail park market shows no signs of slowing. Developers are increasingly focusing on larger projects: currently, 52 retail parks above 5,000 sq m are under construction or expansion, including 10 projects exceeding 15,000 sq m.
The largest is Osada in Żyrardów, which will deliver 33,000 sq m GLA, signaling how retail parks are evolving into alternatives to traditional regional shopping centers.
“These larger formats have proven attractive to a broader tenant mix, drawing not only everyday goods operators but also value fashion brands, gastronomy, and services. As a result, retail parks are transforming from purely local shopping destinations into versatile retail hubs meeting a wider range of consumer needs,”
commented Artur Czuba, Director, Investment at Avison Young.
Key Market Players
Around 45% of retail park stock (over 5,000 sq m GLA) is held by the top 10 owners. Pradera leads with 9% market share, followed by Saller (8%), BIG Poland (6%), and Trei Real Estate (5%). The remaining shares are fragmented, with no single owner above 3%.
“BIG’s entry into Poland in 2022 marked the start of a focused, long-term growth strategy targeting mid-sized cities with strong potential. We acquire and develop assets in prime locations with carefully curated tenant mixes and clear value growth prospects. Since entering Poland, BIG has built a portfolio of 10 fully leased retail parks with a combined 200,000 sq m GLA, securing a 6% market share in this expanding segment,”
said Eran Levy, CEO of BIG Poland.
Projects Under Construction
As of August 2025, the seven most active developers of retail parks and small convenience parks account for nearly 50% of new supply. Saller leads with a 13% share of pipeline space, followed by LCP Properties with 10%. Ownership of parks under construction remains highly fragmented, with around 40 active developers.
The total retail park pipeline is estimated at 510,000 sq m, with 57% of new supply in towns under 50,000 residents and 19% in Poland’s eight largest urban areas. Notably, only 15 of the 64 projects exceed 10,000 sq m.
Over the past five years, 1.7 million sq m of retail park space has been added, compared with just over 500,000 sq m GLA in traditional shopping centers.
What Does a Typical New Retail Park Look Like Today?
- Located in a town of 10,000–50,000 residents (52%)
- 5,000–10,000 sq m GLA (62%)
- Positioned on a commuter route, “on the way home” (40%)
Author: Paulina Brzeszkiewicz-Kuczyńska, Research and Data Manager, Avison Young
Source: CEO.com.pl