Poles are saving more, but most household financial assets are still held in cash and bank deposits. Personal Investment Accounts, known by their Polish acronym OKI, are intended to encourage households to invest a larger share of their savings in the capital market by offering preferential tax treatment. Analysts at PKO BP Brokerage estimate that the scheme could bring more than PLN 23 billion in gross inflows to the Polish equity market by 2030, while more than 2 million people could open OKI accounts. A greater role for domestic savings in financing companies could also support faster economic growth. If the legislation is signed by the president, the new system is expected to take effect on January 1, 2027.
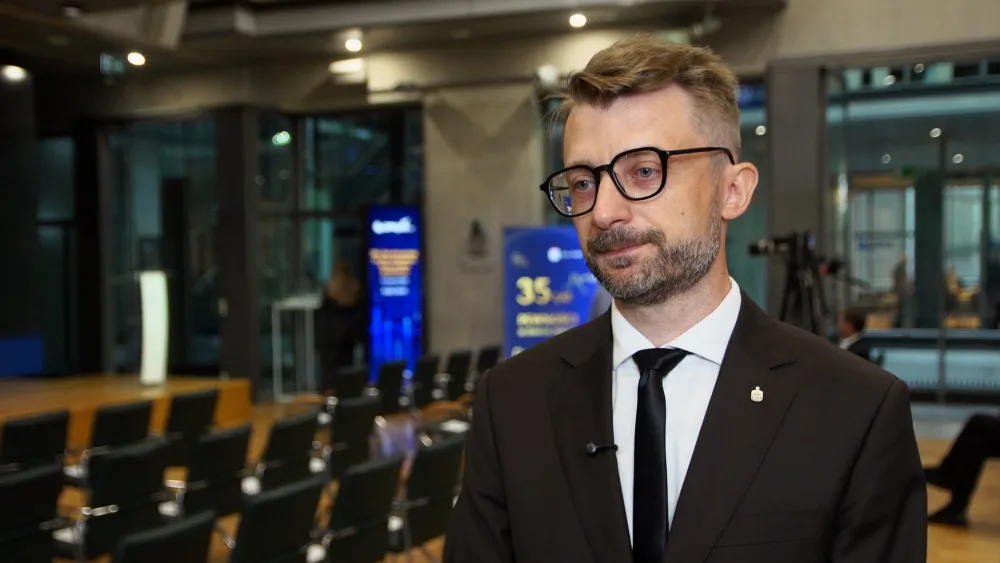
“OKI is a solution that could change the landscape of Poland’s capital market and, in the longer term, the Polish economy as well. On the one hand, new funds flowing into the capital market as a result of promoting regular saving will increase its depth and liquidity and give a broader range of companies and issuers access to capital. On the other hand, many studies indicate that a more developed stock market has a positive long-term impact on the cost of capital, risk premiums and the quality of capital allocation, which should ultimately translate into stronger economic growth,” Kamil Kliszcz, Deputy Director at PKO BP Brokerage, told Newseria.
According to a report by PKO BP Brokerage, cash and bank deposits currently account for 67% of Polish households’ financial assets, while capital market-related products represent 27%.
In the euro area, the proportions are very different, at around 40% and 56% respectively. Direct and indirect equity investments account for only about 5% of household financial assets in Poland.
PKO BP analysts estimate that assets accumulated through the OKI scheme could exceed PLN 100 billion within three years and approach PLN 200 billion within five years.
Between 2027 and 2030, the Polish equity market could receive around PLN 23 billion in gross inflows, equivalent to approximately PLN 15 billion on a net basis.
Tax incentives are widely used to encourage long-term investment
“Programmes that encourage regular saving by offering various tax or regulatory incentives are quite common around the world and across Europe. Poland already has several similar mechanisms, although they are mainly focused on retirement savings,” Kliszcz said.
Comparable instruments supporting long-term investment have operated successfully in countries including Sweden and the United Kingdom.
However, investment culture in those markets was already significantly stronger before the introduction of such programmes.
According to figures cited in the report, around 90% of people in Sweden use brokerage services, while the proportion in the UK is approximately 50%.
In Poland, brokerage accounts are held by around 15% of employed people, while approximately 16% have investment fund accounts. On mature European Union markets, the corresponding averages are around 26% and 32%.
“The success of such a programme depends on many factors. The solution has to be simple and easy for customers to understand, and it should not contain restrictions that discourage participation. Success also depends heavily on the determination of all market participants, how the programme is promoted, how customers are educated, how efficiently market institutions operate and whether the product is offered in a customer-friendly way without regulatory barriers or conflicts between individual market participants,” Kliszcz said.
More than 2 million OKI accounts could be opened
Experience from Sweden and the United Kingdom also shows that the popularity of investment schemes offering tax incentives tends to build gradually.
PKO BP Brokerage forecasts that around 800,000 new OKI accounts could be opened annually during the first two years of the programme. Another approximately 500,000 accounts could be added in the following year.
That would bring the total number of accounts to around 2.1 million after three years.
“The assumptions behind OKI appear to meet the criteria of simplicity and attractiveness, both in terms of using the product and the tax advantages associated with opening an account,” Kliszcz said.
“In our view, this is therefore a good idea that addresses a structural challenge: Polish households are saving more, but the structure of those savings is still not optimal when it comes to building long-term capital and diversifying household investment portfolios.”
Polish households are saving more
The PKO BP report shows that Polish households are not only putting aside more money but are also becoming increasingly willing to invest part of their accumulated savings.
The household savings rate increased from an average of around 6.5% of disposable income in the previous decade to 9% in 2025 and 9.6% in the first quarter of 2026.
Funds allocated to financial investments represented the equivalent of approximately 7% of GDP, driven primarily by growing interest in investment funds.
According to the report’s authors, OKI could encourage households to direct a larger share of their savings towards investments offering potentially higher long-term returns, particularly equities.
“The solution is attractive both to investors who are already active in the bond and equity markets and to households that are only beginning to consider where to place their financial surpluses and are looking for alternatives to bank deposits and savings accounts,” Kliszcz said.
Shares, ETFs, funds and bonds on a single account
Under the OKI framework, investors will be able to hold different types of financial assets within a single account, including shares, investment funds, ETFs, bonds and deposits.
The legislation provides preferential taxation for assets held in an OKI account up to a value of PLN 100,000.
For bank deposits and government bonds, a separate limit of PLN 25,000 will apply.
“The OKI structure provides for a threshold up to which the investor is exempt from capital gains tax. Once that threshold is exceeded, taxation applies under different rules — not to the investment gain itself, but to the value of the assets,” Kliszcz explained.
“If a household wants to invest its financial surplus in products offering a potentially higher rate of return, this structure should provide additional tax benefits over the medium term compared with a traditional brokerage account subject to capital gains tax.”
Poland wants more household savings to finance companies
One of the main objectives of the OKI programme is to increase the role of the capital market in financing the Polish economy.
According to the report, the market capitalisation of companies listed on the Warsaw Stock Exchange currently represents around 31% of Poland’s GDP.
The European Union average is approximately 63%, while in countries such as Germany and Spain the figure is around 65%.
The authors argue that directing a greater share of domestic household savings into the capital market could improve companies’ access to financing and reduce Poland’s dependence on foreign capital.
A deeper domestic investor base could also improve market liquidity and make the Warsaw Stock Exchange a more attractive source of financing for both existing listed companies and businesses considering an initial public offering.
If the OKI programme develops in line with PKO BP Brokerage’s forecasts, it could therefore have consequences extending well beyond household investment portfolios. By shifting part of Polish savings from deposits and cash into productive capital, the scheme could strengthen the domestic capital market and increase the role of Polish investors in financing economic growth.